Best Business Credit Cards for a New LLC
A new LLC's first credit card is less about rewards and more about capital access: separating business spend from day one, building a credit file the entity can use later, and covering the software subscriptions and office supplies that show up before the first invoice does. The five cards below are the ones we'd point a brand-new LLC to first, chosen for approval odds with no trade history, no annual fee, and reporting behavior that actually helps a new entity rather than just its owner's personal score.
This review sits inside our full hub on Credit Cards. Compare it against every other card we cover before you decide.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Funding in as little as 24 hours
Advertiser Disclosure: This page contains affiliate links. We may receive compensation with no additional cost to you. Learn more.
How We Picked These Cards
We looked for five things a brand-new LLC actually needs from a first card: an approval process that doesn't require existing business trade history, no annual fee in year one, an issuer that won't let ordinary usage bleed onto the owner's personal credit report, and a rewards structure that matches costs a new entity actually has, software, office supplies, gas, and client meals, not travel perks nobody's using yet. None of the five below require the LLC to have revenue, an EIN alone is enough to apply, and every one carries a personal guarantee, which is standard for a card with no business credit history behind it.
The 5 Best Business Credit Cards for a New LLC
Blue Business Cash
A flat 2% cash back on the first $50,000 in combined purchases each year (1% after) with no annual fee makes this the simplest default for a new LLC that doesn't want to track bonus categories. American Express's approval process is friendlier to thin-file entities than most competitors, and the card carries an intro 0% APR period on purchases, useful for a first big vendor payment.
Business Advantage Customized Cash Rewards
You choose your own 3% category, gas, office supply, travel, or a few others, then earn 2% on the next $50,000 in combined purchases at gas stations and wholesale clubs, and 1% on everything else. Bank of America Preferred Rewards members get a 25-75% bonus on top of that. No annual fee.
Spark Cash Select

No annual fee paired with no foreign transaction fee is a rare combination, and it is why this card earns a place in a new LLC's first application round despite an unremarkable 1.5% flat rate. Nothing has to be elected or activated, employee cards are free, and there is an intro 0% APR period on purchases. The structural fact that matters more than the earn rate is reporting behavior: Capital One sends full ongoing activity, including balances and utilization, to the owner's personal credit reports at all three bureaus. No other card on this page does that routinely. For an owner who expects to apply for a mortgage or an SBA loan within the year, that alone is a reason to choose differently.
Ink Business Unlimited
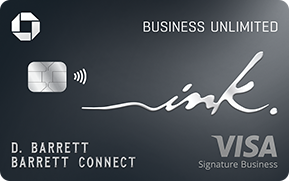
A new LLC spends on things no bonus category anticipates: a deposit to a fabricator, a contractor invoice, state filing fees, a used van. This card pays a flat 1.5% on all of it with no categories and no caps. There is no annual fee, there is an intro 0% APR period on purchases, and employee cards are free and unlimited for the moment a first hire arrives. Chase reports the account to business credit bureaus and keeps it off your personal credit report unless it goes seriously delinquent, which is precisely the separation a new entity wants. One eligibility point before applying: Chase will likely decline you if you have opened five or more personal cards in the past 24 months.
Triple Cash Rewards Visa Business
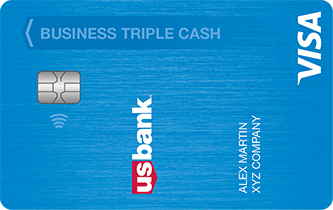
The costs a new LLC takes on in month one are unusually predictable, and this card is built around them. It earns 3% at gas and EV charging stations, office supply stores, cell phone service providers and restaurants, 5% on prepaid hotels and car rentals booked through the U.S. Bank Travel Center, and 1% elsewhere. There is no annual fee, an intro 0% APR period on purchases, and free employee cards. The quiet standout is an annual statement credit for recurring software subscriptions such as QuickBooks and FreshBooks, which lands well when the entity is signing up for bookkeeping in week one. A foreign transaction fee applies.
Which Situation Matches Your LLC
Brand-new, no revenue yet: Every card above evaluates the owner's personal income and credit, not the LLC's revenue, so a pre-revenue entity can still apply the same day it's formed. Household income counts too, not just what you personally earn.
EIN-only, want to keep it off your personal report: No issuer will skip the personal guarantee for a brand-new entity with no trade history, but Chase and American Express keep on-time activity off the owner's personal credit file. Capital One reports ongoing activity to personal bureaus regardless of the guarantee, so it's the one to avoid if separation matters more than the earn rate.
Fair credit or no credit history: Approval odds drop with any of the five above once a score is meaningfully below the high 600s. A secured business card, or a card explicitly underwritten on cash flow rather than credit score, is the more realistic starting point until the file builds.
After a bankruptcy: Most major issuers want two to four years of distance from a discharge before a standard unsecured card approves. A secured card rebuilds a usable file in the interim without waiting out the full window.
Single-member LLC: You apply exactly as any other LLC would; a single-member entity isn't treated differently by the underwriting on any of the five cards above.
Minority-owned or veteran-owned business: Card underwriting doesn't factor ownership status, but it's worth pairing a card application with a look at SBA-backed and mission-driven lender programs built specifically for minority-owned and veteran-owned businesses, which can offer better long-term terms than a card ever will.
Business Credit Card vs. Line of Credit vs. Term Loan
A card covers the small, recurring stuff: software, supplies, a client lunch. It does not cover a build-out, an opening inventory order, or payroll while receivables sit unpaid, and card limits for a brand-new entity are typically modest. A business line of credit gives a new LLC a larger, reusable pool of capital to draw against as needs come up, without reapplying each time. A term loan makes more sense for a single, larger, one-time need, buying equipment, funding a specific expansion, where you want a fixed payment and a fixed payoff date rather than a revolving balance.
How to Choose a Business Credit Card for a New LLC
Treat the first card as a bookkeeping instrument: Clean separation between business and personal spend from the entity's first transaction is worth more at tax time than a fraction of a percent in rewards.
Check where the account will report: Chase, American Express, and U.S. Bank do not routinely report business card activity to the owner's personal file when it is paid on time. Capital One does. If a mortgage application is coming, that difference outweighs the earn rate.
Sequence around Chase 5/24: Five or more personal card openings in the past 24 months makes a Chase approval unlikely. An approved Chase business card does not add to your own 5/24 count, because it never appears on your personal report.
New LLC Business Card Questions
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
More on this topic from the Quordx Capital library.
Keep exploring credit cards
Important Disclosures
Quordx Capital is a business funding broker, not a lender. We facilitate introductions between U.S. small and medium-sized businesses and lenders or capital providers in our network. All credit decisions, funding amounts, rates, fees, repayment terms, and timelines are determined solely by individual lenders based on their own underwriting criteria.
Funding figures and timelines shown on this page are illustrative and represent ranges within our lender network, they are not guarantees and individual outcomes may vary based on business profile, industry, time in business, revenue, credit history, and lender availability. Not all applicants qualify for every product.
The initial inquiry does not impact your personal credit score. Some lenders may perform a hard credit pull during underwriting; Quordx only authorizes such checks with your specific consent for the lender presenting an offer. Applicants are protected under the Equal Credit Opportunity Act (ECOA) from discrimination based on race, color, religion, national origin, sex, marital status, age, or because all or part of an applicant's income derives from any public-assistance program.
This Site is intended for commercial, business-purpose financing for U.S. businesses only. Not available for consumer loans, residential mortgages, or owner-occupied real estate. Quordx may receive compensation from lenders when applications result in funded transactions. This does not change the rate, fee, or terms offered to you. See our Advertiser Disclosure for details.
By submitting an application or contact information, you consent to be contacted by Quordx and its lending partners via phone, text, and email, including by automated means, regarding your funding inquiry. Consent is not a condition of receiving funding. Message and data rates may apply. Reply STOP to opt out. See our Privacy Policy and Terms of Service.