Veteran Business Loans: What Your Service Changes and What It Doesn't
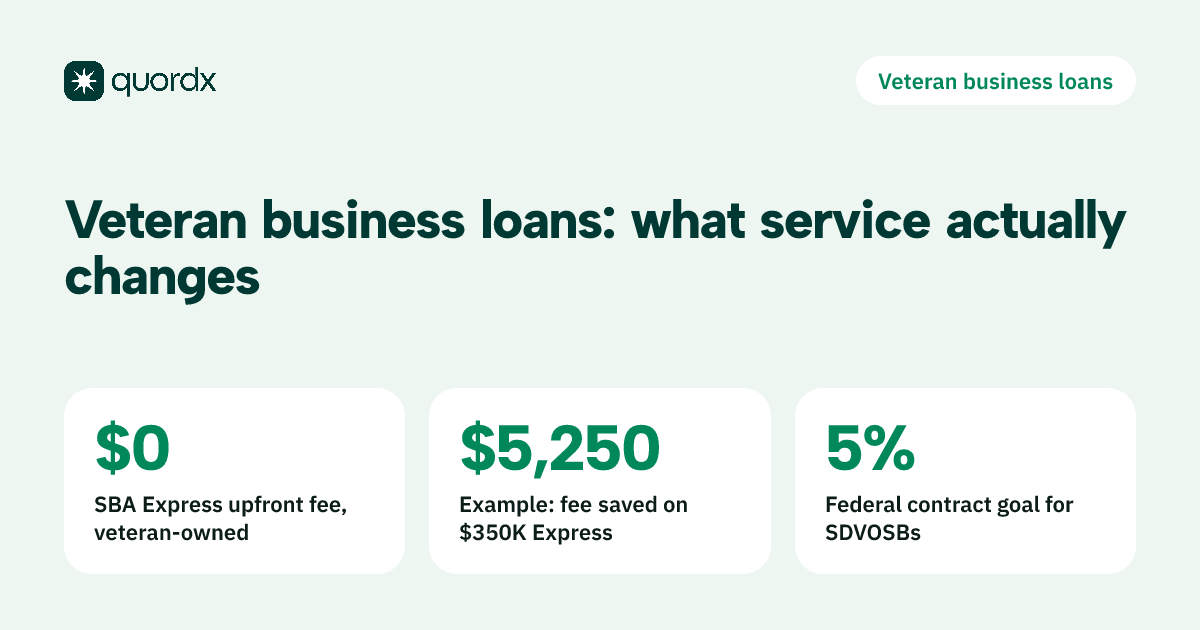
There is no separate federal business loan just for veterans: a veteran-owned business applies for the same loans as any other and is underwritten on the same numbers. Service changes a few specific things. SBA Express loans (up to $500,000) carry a $0 upfront guaranty fee for businesses owned and controlled by a veteran or a veteran's spouse, the Military Reservist EIDL covers a business hurt when an essential employee is called to active duty, the Veteran Small Business Certification opens federal contract set-asides, and SBA funds free training and counseling. Credit, cash flow, collateral and the lender's decision work the same as for everyone else.
The short version: If you need $500,000 or less and qualify, ask lenders for an SBA Express loan, because the fee waiver is real money on the bigger loans. Above $500,000, veteran status does not cut the SBA fee. If you sell to the government, get certified; if a key employee is a reservist, know the Military Reservist EIDL exists before the orders arrive.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Decisions typically in 24 to 48 hours
Common Reasons Operators Apply
Veterinary practices commonly use Quordx-matched funding for situations like these:
- Practice acquisition or partner buy-in costs
- Bridging payment cycles for pet insurance and care plans
- Boarding facility expansion or hospital build-out
- Surgical, dental, and diagnostic imaging equipment
What veteran status changes on a business loan, and what it doesn't
Here is the current picture as of October 2026, item by item.
| Item | Different for veterans? | What actually applies |
|---|---|---|
| SBA Express upfront guaranty fee | Yes | $0 for businesses owned and controlled by a veteran or a veteran's spouse |
| Standard SBA 7(a) fee (any size) | No | Same FY 2027 fee table as every borrower |
| Military Reservist EIDL | Yes | Only if an essential employee is called to active duty |
| Federal contract set-asides | Yes | Through VOSB and SDVOSB certification with SBA |
| Training and counseling | Yes | Boots to Business, VBOCs and other free SBA programs |
| Interest rate caps | No | Same SBA maximums by loan size |
| Credit, cash flow, collateral | No | Lenders underwrite the business the same way |
| SBA ownership citizenship rule | No | All owners must be U.S. citizens or nationals |
| Grants to start or grow a business | No | SBA does not offer them to any business |
Grants are the most common misunderstanding: SBA states plainly that it does not provide grants for starting and expanding a business (SBA). Its veteran grants go to the organizations that train and counsel veterans, not to individual businesses.
The $0 SBA Express fee for veteran-owned businesses
Every SBA 7(a) loan normally carries an upfront guaranty fee, charged as a percentage of the part of the loan SBA guarantees. For SBA Express loans to a business owned and controlled by a veteran or a veteran's spouse, that fee is $0, by statute, and SBA's notice for loans approved October 1, 2026 through September 30, 2027 confirms it (SBA Information Notice 5000-881797).
How much the waiver saves
SBA Express loans top out at $500,000 and carry a 50% guaranty. Under the FY 2027 fee table, the fee is 2% of the guaranteed portion on loans of $150,000 or less and 3% on loans from $150,001 to $700,000.
| Express loan | Guaranteed portion (50%) | Normal FY 2027 fee | Veteran-owned fee | Max variable rate (prime 7.00%) |
|---|---|---|---|---|
| $100,000 | $50,000 | $1,000 (2%) | $0 | 13.00% (prime + 6.0) |
| $150,000 | $75,000 | $1,500 (2%) | $0 | 13.00% (prime + 6.0) |
| $350,000 | $175,000 | $5,250 (3%) | $0 | 11.50% (prime + 4.5) |
| $500,000 | $250,000 | $7,500 (3%) | $0 | 10.00% (prime + 3.0) |
The waiver touches the fee, not the rate: The interest rate cap, the term and the lender's credit standards are the same as for any Express borrower. And because SBA guarantees only half of an Express loan, the lender keeps more of the risk and may hold applicants to a tighter credit standard than on a standard 7(a) loan.
Who counts as a veteran for the fee waiver
The statute covers more than veterans (15 U.S.C. 636(a)(31)(G)). It includes service members eligible for the military's Transition Assistance Program, members of a reserve component, the spouse of anyone in those groups, and the surviving spouse of a service member who died on active duty or from a service-connected disability. The lender has to document your eligibility in its loan file, so bring proof of service when you apply.
Decision rule: if you need $500,000 or less and your lender offers SBA Express, ask for it by name and ask for the veteran fee waiver in writing. If you need more, a standard 7(a) loan is the route, and the fee applies in full: on a $1,000,000 loan with a 75% guaranty, that is 3.5% of $750,000, or $26,250, veteran or not. Our SBA Express loan guide covers how lenders run the program.
Estimate your funding
Answer a few questions about your business to see a likely range.
Military Reservist EIDL: when an essential employee is called up
The Military Reservist Economic Injury Disaster Loan (MREIDL) helps a small business with losses when an essential employee in the Reserves or National Guard is called to active duty. You apply to SBA directly, not through a bank, and SBA must first find that the business cannot get the credit elsewhere without undue hardship (SBA).
- Amount: up to $2 million, limited to the actual economic injury SBA calculates, less any business interruption insurance.
- Cost: interest capped at 4%, the first payment deferred 12 months with no interest building in that period, and a term of up to 30 years with no prepayment penalty.
- Collateral: required on loans over $50,000. SBA says it will not decline for lack of collateral but will take what is available.
- Uses: ordinary and necessary operating expenses. It cannot replace lost income or profits, refinance debt or pay for expansion.
- Filing window: opens when the essential employee receives notice of an expected call-up and closes one year after that person is released from active duty.
If a key person in your business serves in the Guard or Reserve, keep this program on file now: The window opens at the notice of call-up, not the deployment date. For other SBA disaster programs, see our guide to emergency business funding.
Veteran Small Business Certification (VetCert) and federal contracts
Since January 1, 2023, SBA rather than the VA certifies veteran-owned small businesses for federal contracting. A veteran-owned small business (VOSB) must be at least 51% owned and controlled by one or more veterans; a service-disabled veteran-owned small business (SDVOSB) must be at least 51% owned and controlled by veterans the VA rates as service-disabled. The federal government aims to award at least 5% of all contracting dollars to SDVOSBs each year (SBA).
Certification is not financing: It gets you into competitions limited to veteran-owned firms; it does not come with a loan or a grant. Where it helps your borrowing is indirectly: a federal contract creates receivables owed by the government, and invoice financing can turn it into cash before the agency pays. Federal receivables have their own assignment rules, so use a factor that has handled government contracts before.
You do not need VetCert for the Express fee waiver: The fee notice asks the lender to document that a veteran or a veteran's spouse owns and controls the business; it does not mention SBA certification.
Free SBA training for veterans and military spouses
SBA's Office of Veterans Business Development runs or funds several training programs (SBA). None of them lend money, but they are a good place to build the business plan and projections a lender will ask for.
- Boots to Business: a two-day, in-person introduction to business ownership, part of the Defense Department's Transition Assistance Program and offered on installations worldwide. It is open to service members, including the Guard and Reserve, and military spouses, free of charge (SBA).
- Boots to Business Reboot: the same idea off-base, for veterans of any era.
- B2B Revenue Readiness: a six-week online course for graduates of Boots to Business or Reboot.
- Veterans Business Outreach Centers (VBOCs): nationwide centers offering business plan workshops, concept assessments, mentorship and training for service members, veterans, and Guard and Reserve members.
- Programs for specific groups: the Women Veteran Entrepreneurship Training Program and the Service-Disabled Veteran Entrepreneurship Training Program.
What lenders look at for a veteran-owned business
Lenders underwrite a veteran-owned business on the same file as anyone else's: personal and business credit, bank deposits and their consistency, time in business, existing debt and, for larger loans, collateral and cash flow coverage. Leadership experience is a real asset in the conversation, but it does not replace two years of tax returns.
The SBA citizenship rule catches some military families: As of October 2026, every direct and indirect owner of an SBA 7(a) or 504 applicant must be a U.S. citizen or U.S. national whose principal residence is in the United States or its territories, and lawful permanent residents may not own any share. If a spouse or partner who holds a green card is a co-owner, the business cannot use those programs until that changes.
Newly separated and starting from zero?: With no revenue history, the realistic first loans are an SBA 7(a) startup loan with real cash in the deal, an SBA microloan or equipment financing for a specific purchase. Our guide to an SBA loan to start a business covers what lenders expect. Be wary of anyone who wants an upfront fee for access to a "veteran grant" or a special veteran loan program; see how to check whether a funding company is legitimate.
Where Quordx fits for a veteran-owned business
Quordx is a broker, not a lender, and it does not place SBA Express loans, so it cannot get you the $0 fee. For an Express loan, start with your own bank or SBA's Lender Match and ask for the veteran waiver up front.
Where Quordx can help is the rest of the lineup, with no veteran premium or discount either way. The lenders it works with generally look for around $17,000 a month in revenue and about a year in business, and SBA loans through Quordx generally start around $400,000. One application, about 10 minutes, reaches lenders for term loans, lines of credit, equipment financing and factoring for government or commercial receivables. Lenders decide, and lenders pay Quordx if a deal funds.
Quordx does not serve Virginia, Connecticut, Missouri or North Dakota. A business in one of those states should go straight to a bank, a credit union or Lender Match.
Questions Business Owners Ask Before Applying
Are there SBA loans just for veterans?
Not as a separate program. Veteran-owned businesses use the regular 7(a), Express, 504 and microloan programs, with one built-in benefit: a $0 upfront guaranty fee on SBA Express loans up to $500,000 for businesses owned and controlled by a veteran or a veteran's spouse.
Can a military spouse get the SBA Express fee waiver?
Yes. The statute covers the spouse of a veteran, a reservist or a service member eligible for the Transition Assistance Program, and the surviving spouse of a service member who died on active duty or from a service-connected disability. The business must be owned and controlled by the eligible person.
Does a service-disabled rating get better loan terms?
Not on SBA loan pricing; the rate caps and fees we found do not change with a disability rating. The rating matters for SDVOSB certification, which opens federal contracts limited to service-disabled veteran-owned firms, and for the Service-Disabled Veteran Entrepreneurship Training Program.
Will being a veteran help me get approved?
No lender rule we know of approves a loan because of service. Lenders decide on credit, cash flow, time in business and collateral, so the best help is a clean file: separate business accounts, current tax returns and a clear use of funds.
Can I get a Military Reservist EIDL if I am the reservist and the owner?
The program covers a business whose essential employee is called to active duty, and SBA's page does not say whether an owner can be that employee. Ask SBA's disaster customer service directly before you count on it.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources
Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures