Business loan with a 600 credit score: what changes between 600 and 680
You can get a business loan with a 600 credit score, mostly from revenue-based lenders, equipment financing and invoice factoring, but many banks and the best-known online lenders publish personal credit minimums above 600. Each step toward 680 clears more of those published floors and usually lowers your price. Even so, in the Federal Reserve's 2025 survey, applicants in the 620 to 719 range got their full request about as often as those below 620; the big jump came at 720.
The short version: At 600, lead with your bank deposits, your invoices or the equipment you're buying, not your score. If you can wait 30 to 60 days, pay card balances below 30% of their limits and dispute any errors first, because a higher score mainly buys a lower price. Compare every offer by total dollars repaid.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Decisions typically in 24 to 48 hours
Where a 600 credit score puts you with lenders
The Federal Reserve's Small Business Credit Survey sorts firms by credit risk using the self-reported score the business borrows on, personal or business, and the weaker one when it uses both. In its 2026 chartbook on firms by credit risk, a personal score under 620 counts as high risk, 620 to 719 as medium risk and 720 or above as low risk.
| Fed credit risk group | Personal score | Got the full amount sought (2025) |
|---|---|---|
| High risk | Under 620 | 30% |
| Medium risk | 620 to 719 | 32% |
| Low risk | 720 or above | 60% |
Read that table carefully: A 600 and a 680 sit in different groups, yet in 2025 their full-approval rates were within two points. Your score sets which lenders will look and what they charge. Your revenue, time in business and existing debt decide most of the rest.
The survey isn't a random sample and the scores are self-reported, so treat it as a direction, not your personal odds.
What changes at each step from 600 to 680
Lenders don't share one cutoff. The useful markers are the minimums that large lenders publish on their own pages. Here is where the ones we track sat when we checked in 2026, without naming who uses which number.
| Your score | What it clears | What a lender sees |
|---|---|---|
| 600 to 619 | Revenue-based lenders with no published floor; factoring; some equipment deals | High risk in the Fed's grouping; the rest of the file has to carry you |
| 620 to 639 | The 625 personal minimum two large online lenders publish | Medium risk; mainstream online term loans and lines start to open |
| 640 to 659 | No new published floor we track | Same doors as the low 600s, usually at a better price |
| 660 to 679 | The 660 minimum one large online line of credit and one big bank publish | Bank small business loans come into view; one online lender lists 675+ as helpful |
| 680 and up | Still short of the "above 700 typically" another big bank states | Better pricing, more lenders, still not bank-preferred |
The jumps that matter are 625 and 660: Moving from 600 to 640 gets you past one common published floor. Moving from 650 to 660 can get you past another. A move inside a band, say 605 to 615, changes little except possibly your price.
See what you could qualify for
Four answers about your business. No credit pull.
Which business loans fit a 600 to 680 credit score
- Revenue-based term loans and working capital loans. Underwritten mainly on several months of business bank statements. Strong, steady deposits can carry a 600 score. Expect shorter terms and higher prices than a bank.
- Lines of credit. Harder below 620, more realistic past 625 and 660 where published floors sit. See lines of credit for bad credit.
- Equipment financing. The machine secures the loan, and a down payment helps offset the score. See what credit score equipment financing needs.
- Invoice factoring. If you bill other businesses, your customers' credit matters more than yours.
- SBA loans. SBA says borrowers must be creditworthy, and each lender judges what that means, so 600 is a hard case and 680 a more realistic one. Details in SBA loans with a 600 credit score.
- Merchant cash advances. Available at 600 and below, and the most expensive option here. Use one only after pricing the others.
How much a higher credit score saves: worked examples
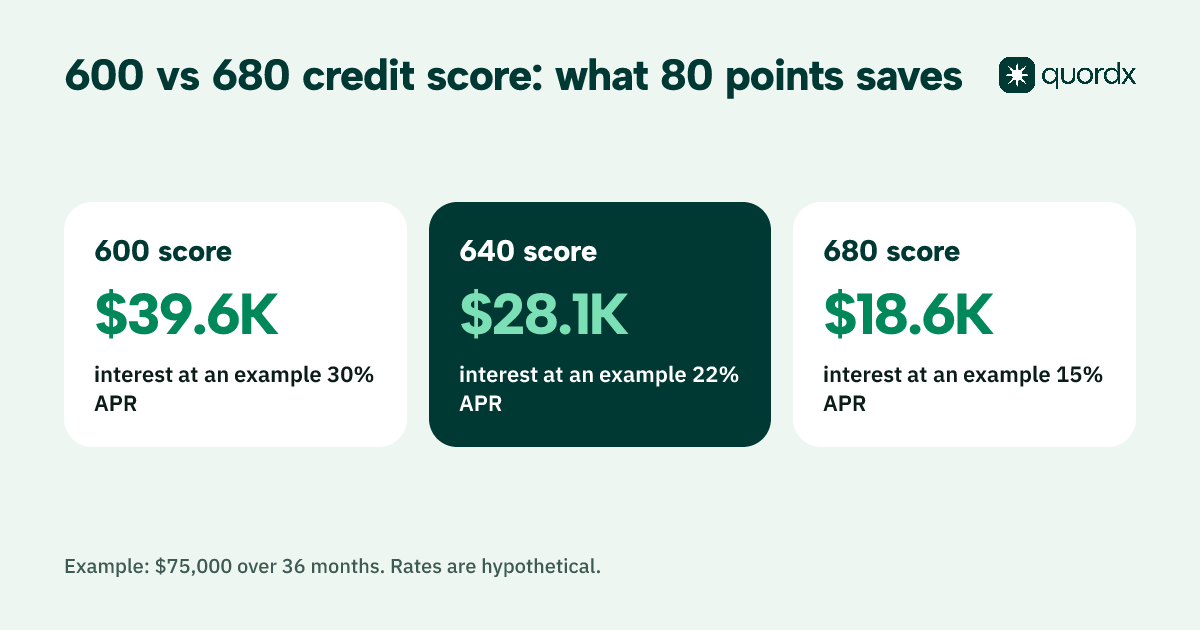
Say you borrow $75,000 over 36 months with monthly payments. The rates below are made up to show how a score step can move price. They are not quotes or market rates.
| Score (example) | Rate assumed | Monthly payment | Total interest |
|---|---|---|---|
| 600 | 30% APR | $3,183.87 | $39,619 |
| 640 | 22% APR | $2,864.28 | $28,114 |
| 680 | 15% APR | $2,599.90 | $18,596 |
In this example, 80 points saves $21,023 in interest and $583.97 a month: Even the 40-point step from 600 to 640 saves $319.59 a month and $11,505 over the loan.
Decision rule: if you can raise your score before you apply, compare the savings with the cost of waiting. Here, waiting two months to go from 600 to 640 is worth about $11,500. If the delay would cost you less than that, say a missed discount or a short-term bridge, wait. If it would cost you a contract or payroll, borrow now and refinance once the score improves.
How to raise a 600 credit score fast before you apply
Nothing legitimate moves a score overnight, but a few steps can count as soon as your accounts next report to the bureaus.
- Pull all three reports. The FTC says you can check each bureau's report free once a week at AnnualCreditReport.com.
- Dispute real errors. The CFPB says the companies that report your data generally must investigate within 30 days and fix or remove what they can't verify.
- Pay revolving balances down. The CFPB notes that experts advise using no more than 30 percent of your total credit limit. With $12,000 owed on $20,000 of card limits, you're at 60%; paying $6,000 brings you to 30%.
- Time the paydown. Ask each card issuer what date it reports your balance to the bureaus, and pay before then so the lower balance is the one that gets reported.
- Get current on anything past due. The CFPB's advice is to get current and stay current.
- Stop applying for other credit. A cluster of new applications can read as financial trouble to a lender.
Skip anyone selling a quick fix: The FTC says no one can legally remove negative information that is accurate and current, and most negative items stay on a report for seven years. The realistic plan is to add on-time history and lower balances on top of the old marks.
Business loan with a 650 credit score: what's different
A 650 sits in the middle of the Fed's medium-risk band. It clears the 625 floors and falls just short of the 660 ones, which makes it the score where a small gain can matter most.
If you're at 650 to 659: check the published minimum of any lender you're considering before you apply. If paying down a card could get you to 660, do that first, because it can open a lender a 650 can't reach. If you need the money now, a 650 is a solid file for revenue-based loans and equipment financing, and your price will depend heavily on your deposits and time in business.
How Quordx helps a 600 to 680 credit score borrower
Quordx is a broker, not a lender, so it can't change how a lender reads your score. Its lenders include some whose credit floors sit inside this band, alongside equipment lenders that weigh the asset and factoring companies that look at your customers. Cash-flow loans through Quordx generally need around $17,000 a month in revenue and about 12 months in business, whatever your score.
For SBA, Quordx can generally only help with loans of roughly $400,000 and up; for a smaller SBA loan, start with SBA's Lender Match. One application, about 10 minutes, reaches several lenders, and some of them run a hard pull when your file is submitted, so ask first if you're timing a score improvement. Lenders pay Quordx when a deal funds. Quordx does not serve Virginia, Connecticut, Missouri or North Dakota.
Questions Business Owners Ask Before Applying
Is 600 a good credit score for a business loan?
It's workable but weak. The Federal Reserve's survey treats a personal score under 620 as high credit risk, and many well-known lenders publish minimums of 625 or 660. Lenders that underwrite mainly on deposits, invoices or equipment are the realistic options at 600.
Can I get an SBA loan with a 600 credit score?
SBA requires a creditworthy borrower and each lender applies its own standard, so a 600 is a difficult file. Strong cash flow, collateral and time in business help. Our page on SBA loans with a 600 credit score covers what lenders weigh.
How fast can I raise my score from 600 to 650?
Lower card balances count once your issuers report them, and disputes are generally investigated within 30 days, but there's no guaranteed timeline. Late payments, collections and other accurate negative items stay on your report, so the gain comes from lower balances and new on-time history.
Does my business credit score matter at 600?
It can. The Fed's survey groups firms by whichever score the business uses to borrow, and a strong business file helps with some lenders. Most small business lenders still pull the owner's personal score, so work on both. Start with how to build business credit.
Will applying for a loan lower my 600 score?
A soft-pull prequalification won't. A hard inquiry can lower it slightly, which is why you shouldn't apply to many lenders in a short span. See whether applying for a business loan hurts your credit.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources
- Federal Reserve Banks: 2026 Firms in Focus, Chartbook on Firms by Credit Risk (2025 Small Business Credit Survey)
- FRED: SBCS, Approved for New Financing, High Credit Risk Employer Firms
- CFPB: How do I get and keep a good credit score?
- CFPB: How do I dispute an error on my credit report?
- FTC: Free Credit Reports
Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures