No credit check business loans: what's real and what isn't
A business loan with truly no credit check is rare. When a lender advertises "no credit check," it usually means a soft pull that doesn't touch your score, or a decision built on the business's own credit and cash flow instead of the owner's FICO. The products that genuinely put little or no weight on your personal score are invoice factoring, financing offered by the platform you already sell through, and some equipment and property-backed deals where the collateral carries the file.
The short version: Ask every lender two questions before you apply: when will you pull my credit, and is it a soft or hard pull? If you invoice other businesses, price factoring first, because your customers' credit does the work. If you sell through a payment platform, check its dashboard for an offer. Walk away from anyone who promises approval regardless of credit or wants a fee before you're approved.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Decisions typically in 24 to 48 hours
Common Reasons Operators Apply
Operators with past credit issues commonly use Quordx-matched funding for situations like these:
- Building or rebuilding business credit through revenue-based products
- A strong revenue profile that traditional underwriting doesn't capture
- Refinancing existing high-cost debt into a more workable structure
- Products structured to qualify based on bank deposits, not credit
What "no credit check" means on a business loan
The phrase covers three different things, and only one of them is close to literal. Before you trust the ad, figure out which one the lender means.
| What the ad says | What it usually means | What to ask |
|---|---|---|
| No credit check | A soft pull to prequalify; a hard pull may come later | "At what step do you run a hard pull?" |
| No impact to your credit score | Applying is soft; accepting an offer or drawing funds may not be | "Does accepting or drawing trigger a hard inquiry?" |
| No personal credit check | The decision rests on business credit, sales data, invoices or collateral | "Will I sign a personal guarantee anyway?" |
| No minimum credit score | The report is read, but no single number disqualifies you | "What else would cause a decline?" |
A soft pull is the honest version: The CFPB explains that a soft inquiry doesn't affect your credit score, while a hard inquiry, the kind lenders run once you apply for credit, can lower it. Most "no credit check" offers are soft-pull prequalifications.
The hard pull often moves, it doesn't vanish: One online line-of-credit lender says it soft-pulls during the application and runs a hard pull at your first draw. A well-known lending marketplace says applying won't affect your score, but accepting an offer from one of its lenders may. Both are honest disclosures. Neither is "no credit check." For how much a hard inquiry actually costs you, see whether applying for a business loan hurts your credit.
Business financing that doesn't weigh your personal FICO
These are the products where something other than your personal score carries the decision. Each one has its own catch.
Invoice factoring: your customers' credit, not yours
A factoring company buys your unpaid invoices and gets paid when your customers pay, so its real risk is your customers, and that's who it underwrites. If you invoice established businesses, a low personal score matters far less here than anywhere else. The catch: it only works for business-to-business sales, and the factor checks that the invoices are real. See how factoring compares with receivables loans.
Platform financing: your sales history
Some payment and ecommerce platforms make loan offers based on what you sell through them. Shopify Capital states there are no credit checks and no impact to your personal score, and says its loans are issued by WebBank and repaid from a fixed percentage of daily sales. Stripe Capital says applying has no impact on your personal score and that eligibility depends on your payment volume and history on Stripe.
The catch: you can't shop these. The platform decides whether you get an offer, and you only see it in your dashboard. Amazon sellers have a similar set of choices, covered in business loans for Amazon sellers.
Some equipment financing: the asset
The equipment secures the deal, so a lender can take it back and resell it. Some equipment lenders put more weight on the asset, your down payment and the reason the credit dipped than on the score itself. Expect a credit pull anyway; what changes is how much one number decides. See how equipment financing works and what lenders check.
Property-backed bridge loans: the real estate
Bridge and hard money lenders lend against a property's value and the plan to repay, often a sale or refinance. Credit is usually a secondary check, but you need real estate with enough equity, and you pay more than a bank would charge on the same property. See how a business bridge loan works.
Sales-based advances: your deposits
A merchant cash advance is decided mostly from your bank statements, and many funders soft-pull only. It's also the most expensive item on this list. We cover it separately in merchant cash advances with no credit check.
See what you could qualify for
Four answers about your business. No credit pull.
Online business loans with no credit check
Applying online doesn't change the underwriting. It changes the order of steps. Online lenders can prequalify you on a soft pull and connected bank data within minutes, which is why "no credit check" shows up so often in online ads. The full review, and often the hard pull, still happens before money moves.
Read the authorization, not the banner: The consent box you tick on an online application says what the lender and its partners may pull. Some marketplace terms authorize hard and soft pulls when you submit a funding request, and some carve out inquiries by their lending partners. If the banner and the terms read differently to you, ask in writing which one applies to your application.
Business credit is a real alternative, for some: An established company with years of payment history at the business credit bureaus can sometimes get a decision on its own file. A young business usually can't. Our page on loans with an EIN only covers when that works.
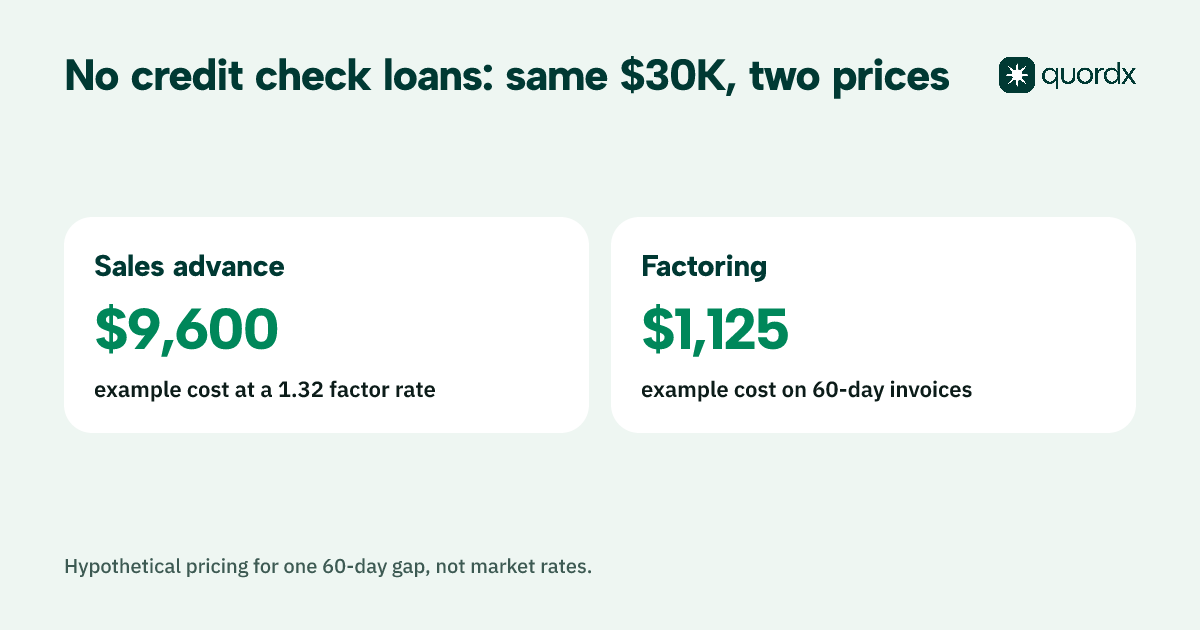
What no credit check costs: the same $30,000, two ways
Say a commercial cleaning company with a 580 score needs $30,000 to cover a 60-day gap while two large customers pay on net-60 terms. The pricing below is made up to show the math. It is not a quote or a market rate.
| Sales-based advance (example) | Invoice factoring (example) | |
|---|---|---|
| What carries the decision | Bank deposits | The two customers' payment record |
| Cash today | $30,000 | $30,000 (80% of $37,500 in invoices) |
| Pricing assumed | 1.32 factor rate | 1.5% of invoice value per 30 days |
| Total cost | $9,600 | $1,125 (3% of $37,500 for 60 days) |
| How it's repaid | 126 daily debits of about $314 | Customers pay the factor; you get the remaining $6,375 |
| Owner's score weighed? | Lightly, often soft pull only | Little, if the customers are strong |
The factoring route costs $8,475 less in this example: and it leaves no daily debit on the account. The advance also runs about six months even though the gap lasts two, so the business keeps paying long after the customers have paid.
Decision rule: if your gap comes from slow-paying business customers, factor the invoices instead of borrowing against deposits. If you sell to consumers and have no invoices, compare any advance by total dollars repaid; our merchant cash advance cost guide walks through it.
No credit check loan scams: the warning signs
"No credit check" is the bait in a lot of loan fraud, because it reaches owners who have already been turned down. The FTC's guidance on advance-fee loans lists the tells, and they apply to business offers too.
- Approval no matter your history. The FTC quotes the scammer's line: "We don't care about your past. You deserve a loan!" A real lender has to look at something before it lends.
- A fee before you're funded. Calling it insurance, processing or paperwork doesn't change it. The FTC says a fee demanded before you get the loan is a reason to walk away.
- No registration where it does business. The FTC notes lenders must register where they do business. Check with your state attorney general or banking regulator.
- A credit repair pitch bundled with the loan. The FTC is plain that no one can legally remove accurate, current negative information from your report. Anyone selling that is selling nothing.
- Pressure to sign today. A real offer still stands after you've read it and run the numbers.
If you're unsure about a company, our checklist on how to tell if a business funding company is legit covers what to verify before you share bank logins or statements.
Which no credit check route fits your business
- If you invoice other businesses, start with factoring. It is the most direct way to take your personal score out of the decision.
- If most of your sales run through one platform, check that platform's dashboard first. An offer there needs no shopping and no new application.
- If you're buying equipment, ask lenders how much weight they put on the asset and your down payment versus the score, and get that answer before they pull.
- If you own commercial property with equity, a bridge loan can work around a weak score, at a price.
- If none of those fit, a soft-pull prequalification from a cash-flow lender is the honest version of "no credit check." Our roundup of loans for bad credit compares those lenders.
Where Quordx fits when you want to protect your score
Quordx is a broker, not a lender, and it can't promise that no lender will pull your credit. Most options can be explored without a hard credit pull, but some lenders pull at the point your file is submitted, so ask before anything goes out. The routes on this page that Quordx can actually reach are factoring for B2B companies (including trucking and construction subcontractors), equipment lenders that look at the story behind the score, and property-backed bridge loans in some states.
It can't get you platform financing, which only comes from your own processor. Its cash-flow loans and advances usually need around $17,000 a month in revenue and about 12 months in business. If that's you, one application of about 10 minutes reaches several lenders at once, with lenders paying Quordx when a deal funds. Quordx does not serve Virginia, Connecticut, Missouri or North Dakota.
Questions Business Owners Ask Before Applying
Can I get a business loan with no credit check at all?
A few products come close: platform financing that states it runs no credit check, and invoice factoring, which leans on your customers' credit. Most other "no credit check" offers use a soft pull to prequalify and may run a hard pull later. Ask each lender when it pulls and what kind of pull it is.
Are there online business loans with no credit check?
Online lenders often prequalify on a soft pull plus your bank data, which doesn't affect your score. The full review, and sometimes a hard pull, comes before funding or at your first draw. Read the credit authorization on the application, because it can allow more than the home page suggests.
Will a lender check my business credit instead of my personal credit?
Some will, if the business has a real file at the business credit bureaus and strong financials. Most small and young businesses still get a personal credit check and a personal guarantee. Building the business file over time is how you shift that balance.
Is invoice factoring a loan?
Usually not. In most factoring deals you sell the invoices and the factor collects from your customers, which is why your customers' payment record matters more than your score. Read whether the deal is recourse, meaning you buy back invoices that don't get paid.
Does a no credit check loan help build my credit?
Only if the lender reports your payments to a credit bureau, and many sales-based products don't. Ask before you sign. If building credit is a goal, a product that reports on-time payments is worth more to you than one that skips the check.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources
Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures